What happened
Texas Instruments reported revenues and earnings above expectations and raised its forward guidance, citing strong demand for its analog and power management chips in AI data centers and industrial markets.
Why it matters
The company is in a multiyear capacity-expansion cycle—building U.S.-based 300mm analog manufacturing—expected to improve cost efficiency, support higher gross margins, and increase supply-chain resilience once assets ramp and utilization normalizes. This positions it to regain its historical free-cash-flow profile while serving diversified end markets (industrial, automotive, aerospace/defense, energy infrastructure).
What to watch
Valuations diverge sharply—the most popular analyst narrative sets fair value at $435.69 per share (the stock was trading near $308.53), framing it as materially undervalued; however, a discounted-cash-flow model arrives at $233.17, suggesting it screens as overvalued. Key risks include whether utilization, margins, or end-market growth will meet the upbeat narrative.
Summaries like this, every morning.
Texas Instruments has emerged as a beneficiary of AI infrastructure buildout, with its latest earnings beat and raised guidance reflecting broad demand across data-center and industrial segments. The company's strategy—investing heavily in domestic manufacturing capacity—aligns with longer-term structural trends: improving gross margins as new fabs ramp, reducing supply-chain risk, and supporting growth in diversified end markets beyond AI alone.
However, the stock's recent momentum presents a valuation puzzle. With a 43.68% three-month return and a 73.80% year-to-date return already reflected in the share price, the question is whether current expectations are realistic. The body presents two competing narratives: one anchored in improved cash generation and margin expansion once new capacity is utilized efficiently, and another—the discounted-cash-flow model—that suggests the stock has already priced in significant upside. The core risk centers on execution: if utilization rates, margins, or end-market growth fall short of the optimistic narrative, the stock could face pressure. Texas Instruments' success will hinge on whether its multiyear fab buildout delivers the competitive-position improvements and cash-flow profile the bull case assumes.
Pick your industry and the AI tools you use, and get news related to your work every day.
Free · 30 seconds with Google · unsubscribe anytimeWhat is AIToday? →
Ask AI anything about this article. The AI reads this article, earlier AIToday articles, and Wikipedia, and cites its sources. Q&As are published on this page for other readers too.
Blackstone's Steve Schwarzman said that a chance encounter led the firm to AI, according to Bloomberg.com
Danaher (DHR) received FDA clearance for AI-powered atrial fibrillation detection
S&P Global reports Q3 on Oct
Tempus AI expanded its drug development collaborations with Bristol Myers Squibb and Pathos AI
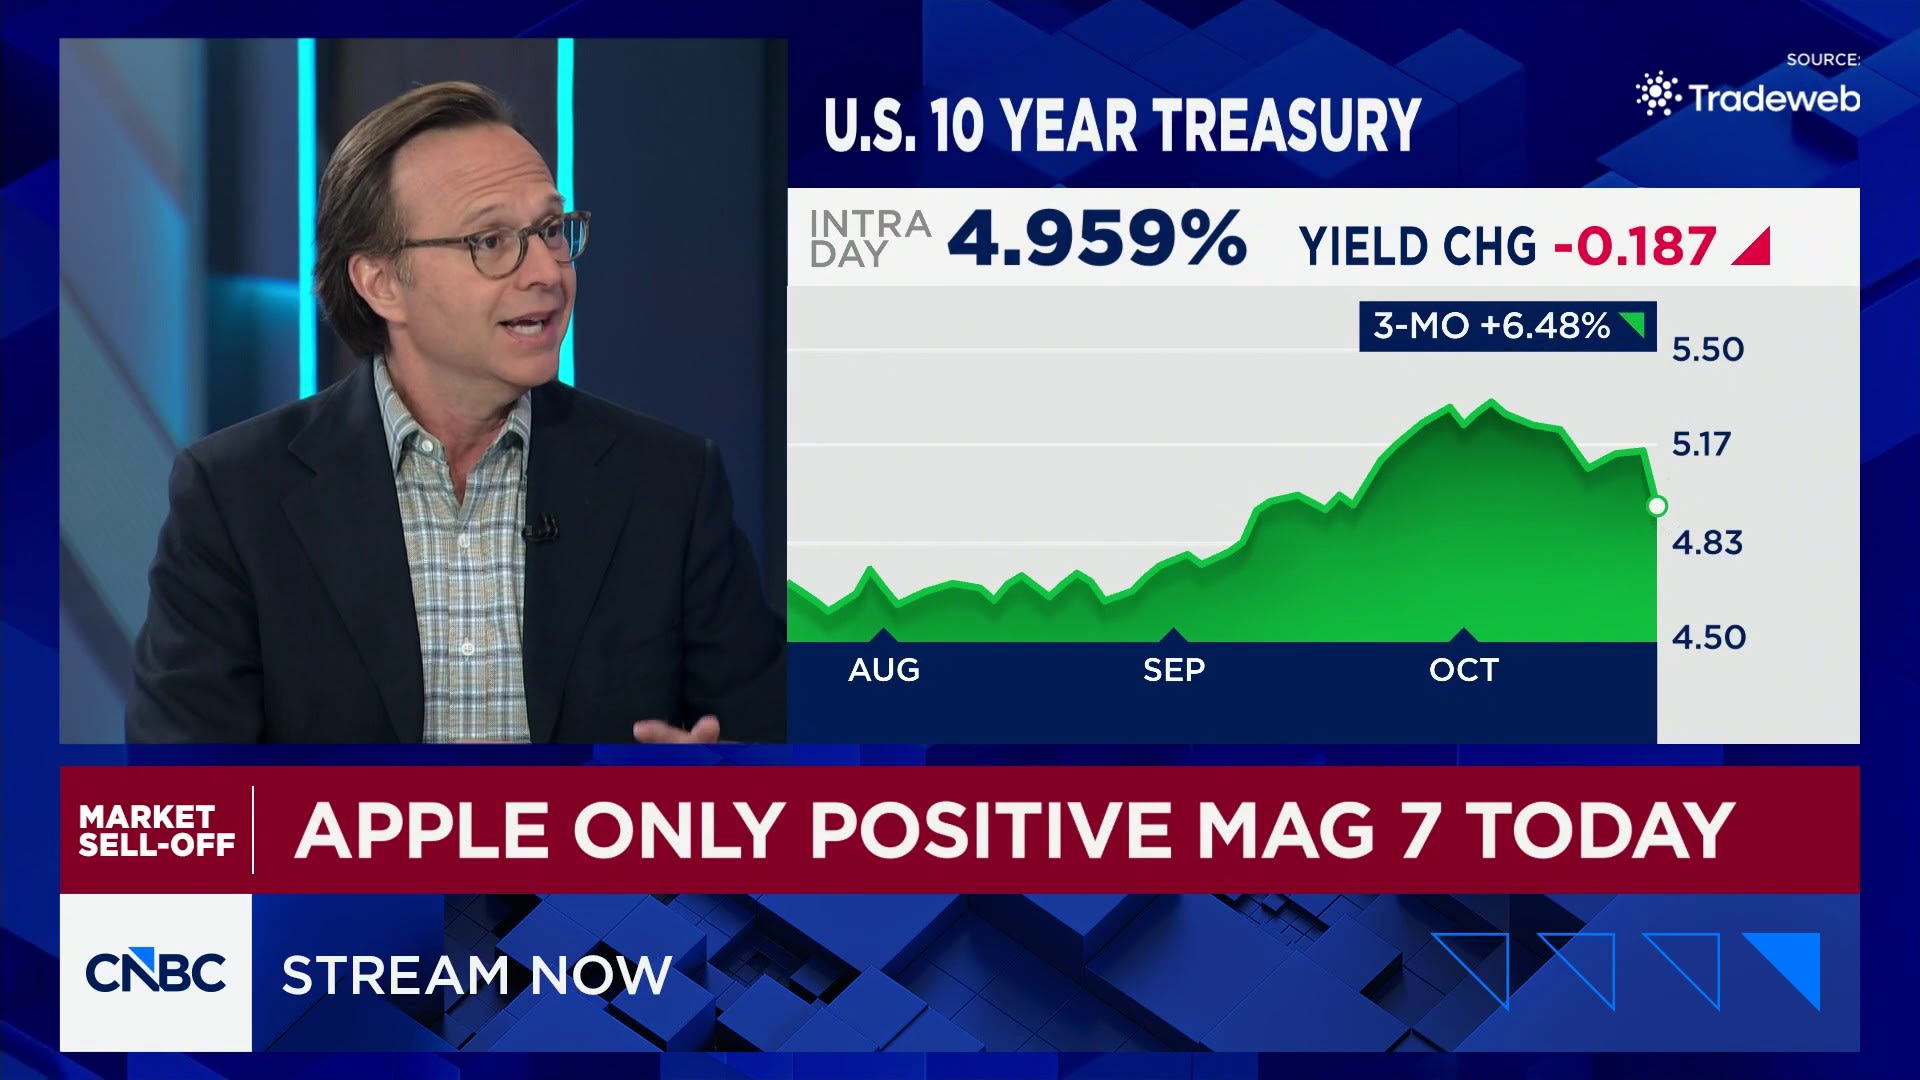
BlackRock Fixed Income Senior Portfolio Manager Jeff Rosenberg said the bond market is reacting rationally to…
Palo Alto Networks Inc. filed its third-quarter 2026 lobbying report on Oct