What happened
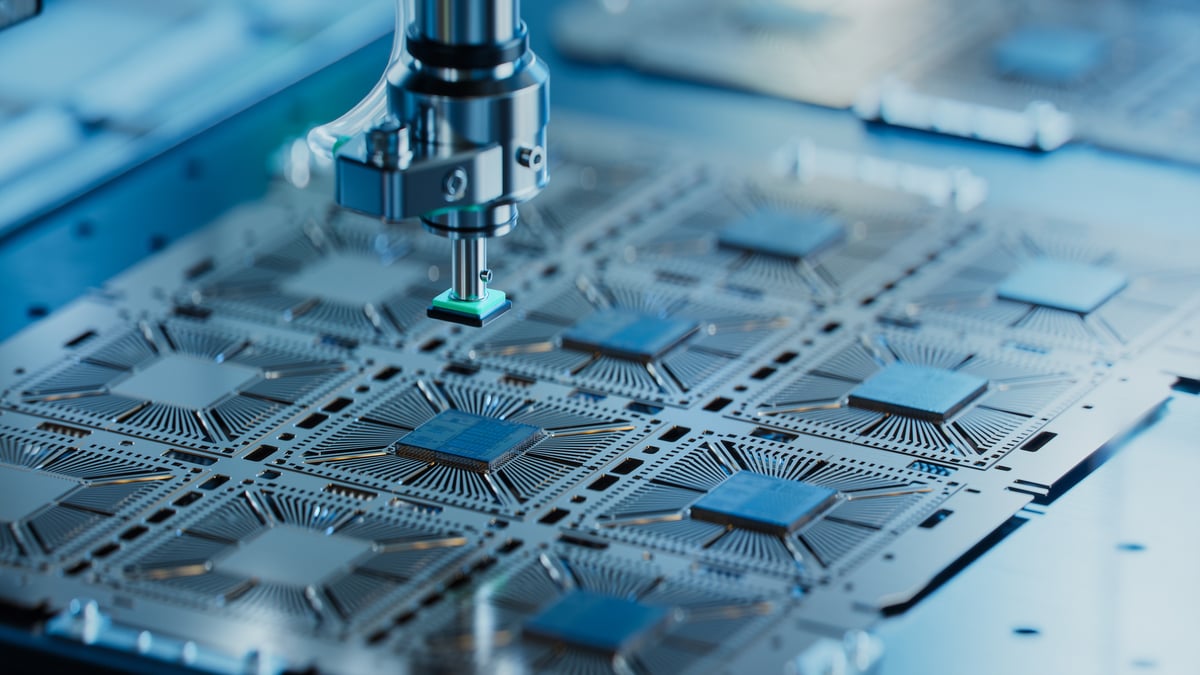
Texas Instruments stock surged 58% year-to-date, driven by a 23% year-over-year revenue growth rate in Q2—its highest in multiple years. The company's analog chips manage electrical power distribution to AI chips, positioning it as a key infrastructure supplier. For Q3, Texas Instruments projects $5.65 billion to $6.15 billion in revenue, implying a 24.5% year-over-year growth rate at the midpoint.
Why it matters
Analog chips serve as the essential middleman between electric grids and AI chips, processing electricity and distributing it without causing overheating. As AI infrastructure demand accelerates, these chips are becoming indispensable to data center operations. Texas Instruments is achieving this growth while reducing capital expenditures (capex fell 60.6% year-over-year in Q2) and maintaining a dividend yield above 2%—a rare combination among fast-growing AI stocks.
What to watch
If Texas Instruments delivers positive sequential growth in Q4 (historically a slower season for the company), it would be a major catalyst. The company could beat the top end of its Q3 guidance if analog chips continue gaining momentum in data centers, positioning it for at least 38% year-over-year revenue growth.
Summaries like this, every morning.
Texas Instruments' path to prominence in AI infrastructure is rooted in a strategic advantage it built over multiple years. The company invested heavily in manufacturing capabilities in the past, positioning itself to supply the critical analog chips that data centers require to operate AI systems efficiently. Now, as AI infrastructure demand accelerates, those past investments are paying dividends—literally. The stock's 58% year-to-date rally reflects investor recognition that analog chips are not optional add-ons but essential components of AI deployment at scale.
What distinguishes Texas Instruments from many peers is its disciplined approach to capital allocation. CEO Haviv Ilan has emphasized that "long-term growth of free cash flow per share is the ultimate measure to generate value," and the company is backing that philosophy with action. While tech giants are rushing to deploy massive capital expenditures for AI, Texas Instruments is actually reducing capex (down 60.6% year-over-year in Q2) and still delivering growth. The company's net income rose 53% year-over-year in Q2—faster than the 23% revenue growth—suggesting that profitability and cash generation are accelerating. This unusual combination of high growth, rising profits, falling capex, and a dividend yield above 2% has created a rare investment profile that can sustain upward momentum.
Pick your industry and the AI tools you use, and get news related to your work every day.
Free · 30 seconds with Google · unsubscribe anytimeWhat is AIToday? →
Ask AI anything about this article. The AI reads this article, earlier AIToday articles, and Wikipedia, and cites its sources. Q&As are published on this page for other readers too.
Bay AI Inc. launched with $50 million — a $37 million Series A led by Battery Ventures and a $13 million seed…
Kora Systems, led by Cyanogen co-founder Kirt McMaster, unveiled a Linux-based desktop OS that runs AI models…
Anthropic will offer 825 million Class A shares at $70 to $78 each, raising $57.75 billion to $64.35 billion…
Google unveiled TPU 8tx, built with AMD for confidential training and inference, and TPU 8i Max, which combine…
IPROS announced five free 20-minute sessions at AI-Industry World 2026, covering Microsoft 365 Copilot, busine…
Stratistics MRC forecasts the AI accelerator and AI semiconductor market will reach $285 billion by 2034, up f…