What happened
Alphabet spent $45 billion on capital expenditures in the second quarter—double the prior year—and revealed in its 10-Q filing that it has committed to spending an additional $811 billion, mostly on AI infrastructure. The company raised its full-year 2026 capex budget to between $195 billion and $205 billion and said capex will "increase significantly in 2027."
Why it matters
Alphabet reported negative free cash flow for the first time since going public in 2004, a sign of the enormous near-term investment required. The company faces a severe shortage of compute capacity as it takes on massive multi-year deals, forcing it to secure chip supply, data center construction, and long-term energy services through take-or-pay contracts locked in years into the future. These commitments signal Alphabet's confidence in sustained AI demand and position it to capitalize on that opportunity, though they will weigh on cash flow over the next several years.
What to watch
Alphabet expects to generally fulfill all of its agreements by 2030, with energy service agreements ranging from two years to 26 years and obligations through 2054. The company is also ramping up direct sales of its custom Tensor Processing Unit (TPU) systems, with inventory jumping from $2.4 billion to $10 billion last quarter—a sign of potential future demand for in-house chip products.
Summaries like this, every morning.
Alphabet's massive AI spending commitment reflects a fundamental shift in how the company is managing its capital allocation. The disclosure of $811 billion in contractual obligations—a jump of nearly $500 billion in just one quarter—signals not only aggressive near-term investment but also a multi-year bet on sustained, growing demand for AI compute. By entering into long-term take-or-pay contracts for chips, data centers, and energy through at least 2030 (and energy services to 2054), Alphabet is locking in supply and pricing certainty even as it acknowledges severe capacity shortages today.
The shift into negative free cash flow, a first since the company's 2004 IPO, is notable but not necessarily alarming to management. Alphabet has disclosed that its core operations remain cash cows and its cloud business is generating strong returns on invested capital. The company is also hedging near-term capacity constraints by increasing third-party provider usage as a bridge until it can build out more internal capacity—a move that will create a short-term margin headwind but is framed as a long-term strategic necessity. Additionally, the jump in inventory from $2.4 billion to $10 billion and the ramp in direct Tensor Processing Unit sales suggest Alphabet sees opportunity not just in consuming AI compute internally but in selling it to external customers, which could help justify the enormous supply-chain commitments it has made.
Pick your industry and the AI tools you use, and get news related to your work every day.
Free · 30 seconds with Google · unsubscribe anytimeWhat is AIToday? →
Ask AI anything about this article. The AI reads this article, earlier AIToday articles, and Wikipedia, and cites its sources. Q&As are published on this page for other readers too.
In Anthropic's IPO roadshow video, co-founder Tom Brown said Claude trains and serves across AWS Trainium, Goo…
Anthropic set a proposed IPO valuation of up to roughly $1.4 trillion, below earlier reported expectations of…
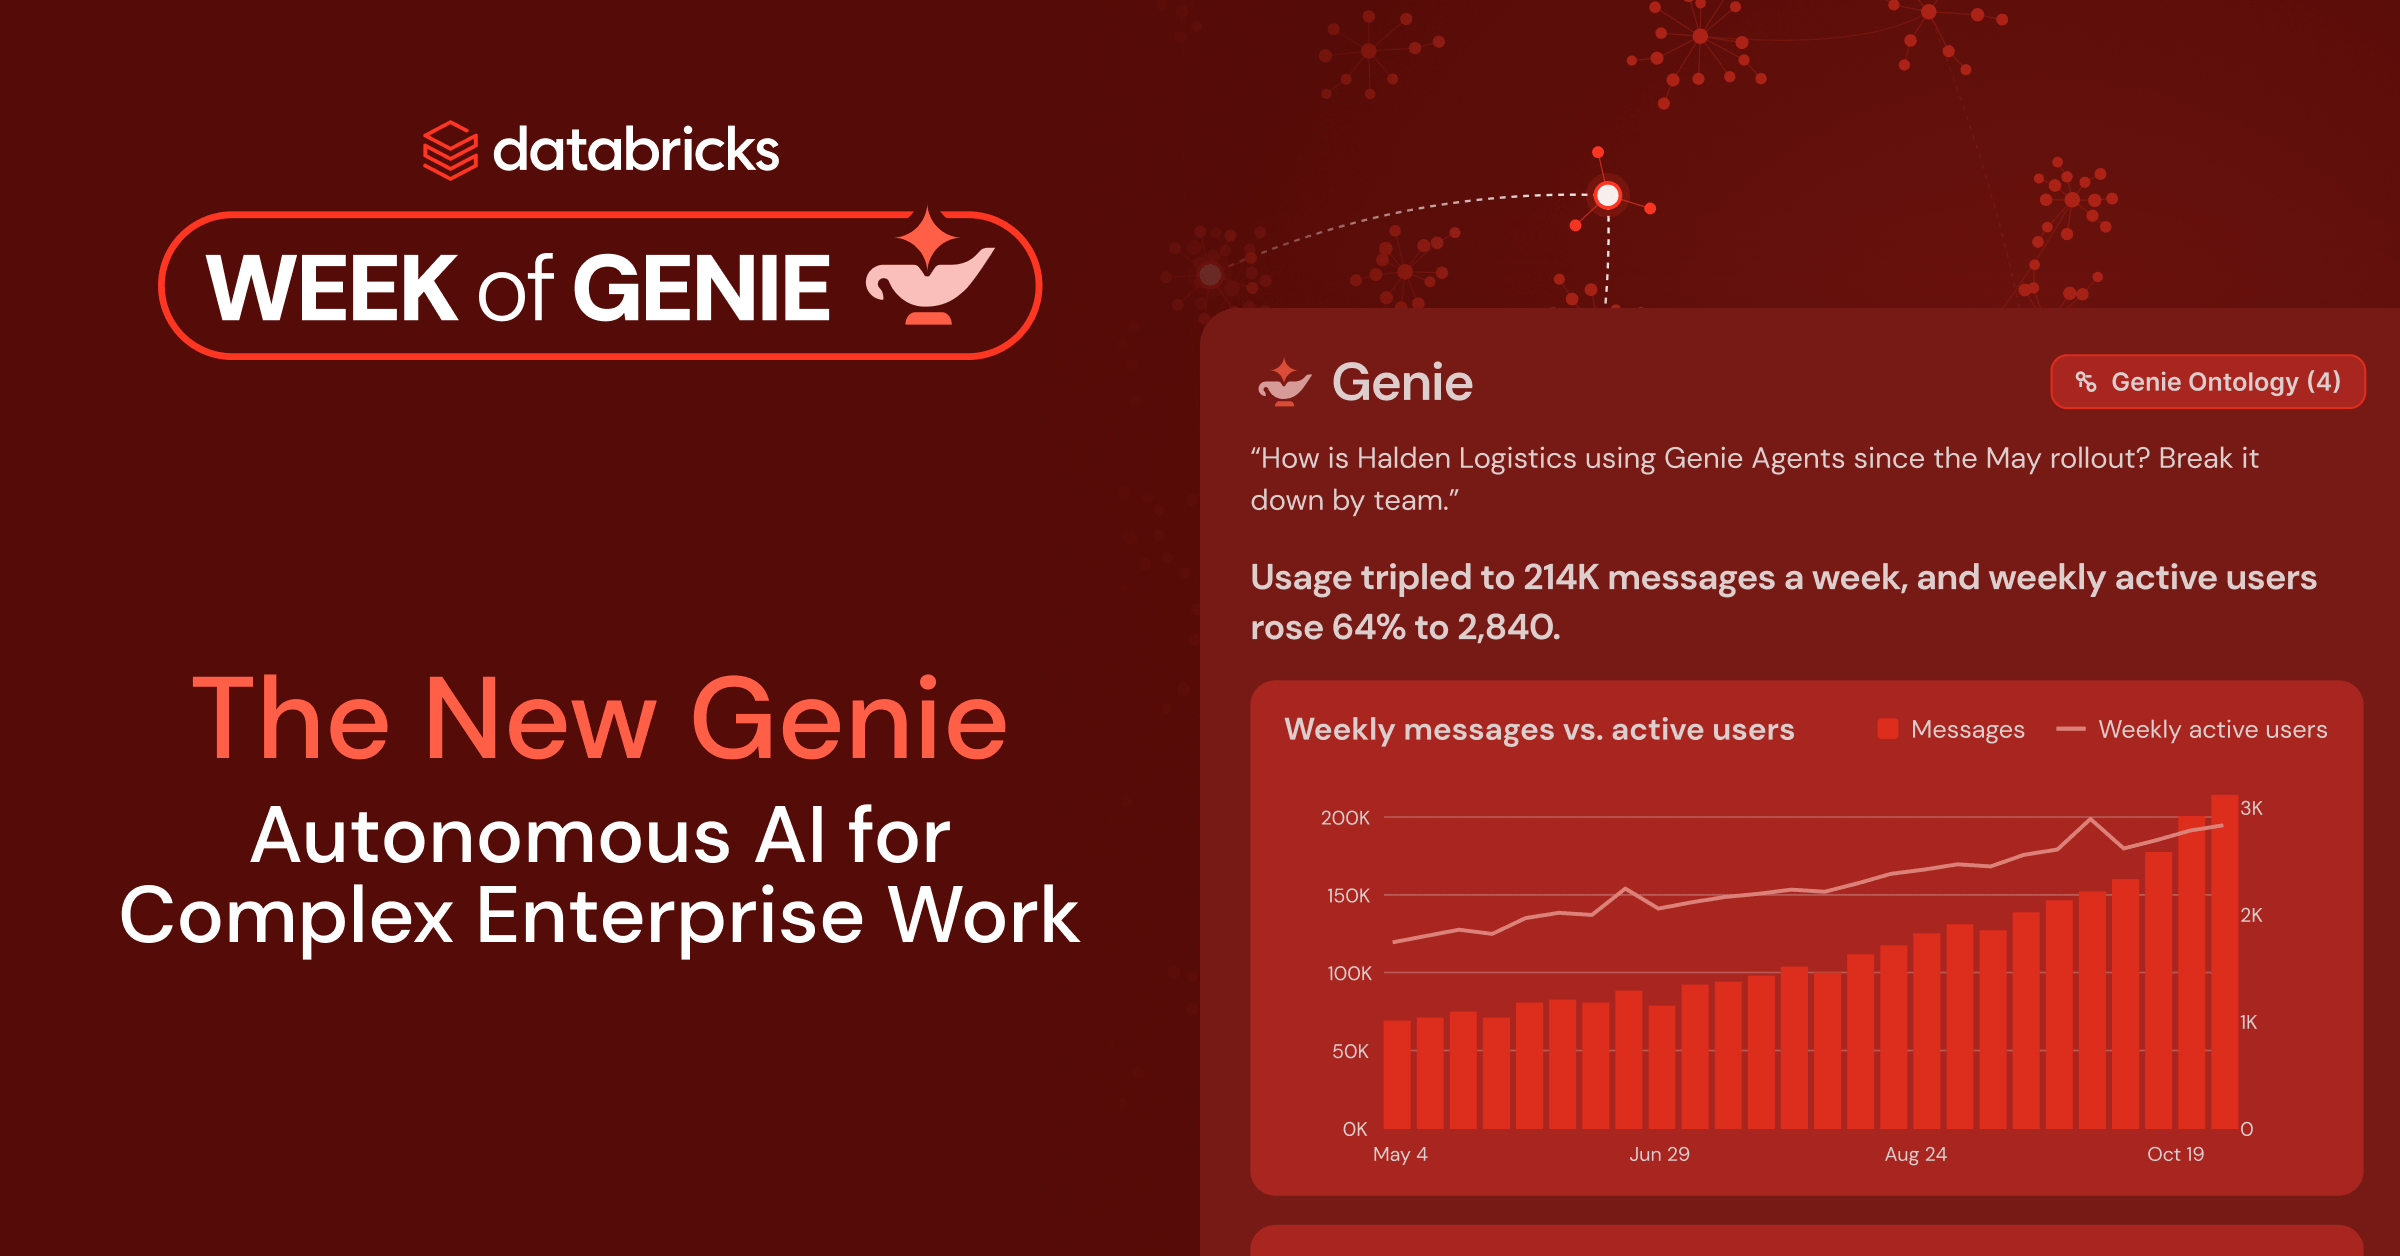
Databricks said Genie One now combines Genie Search across tools like Google Drive, Jira and Confluence, in-co…
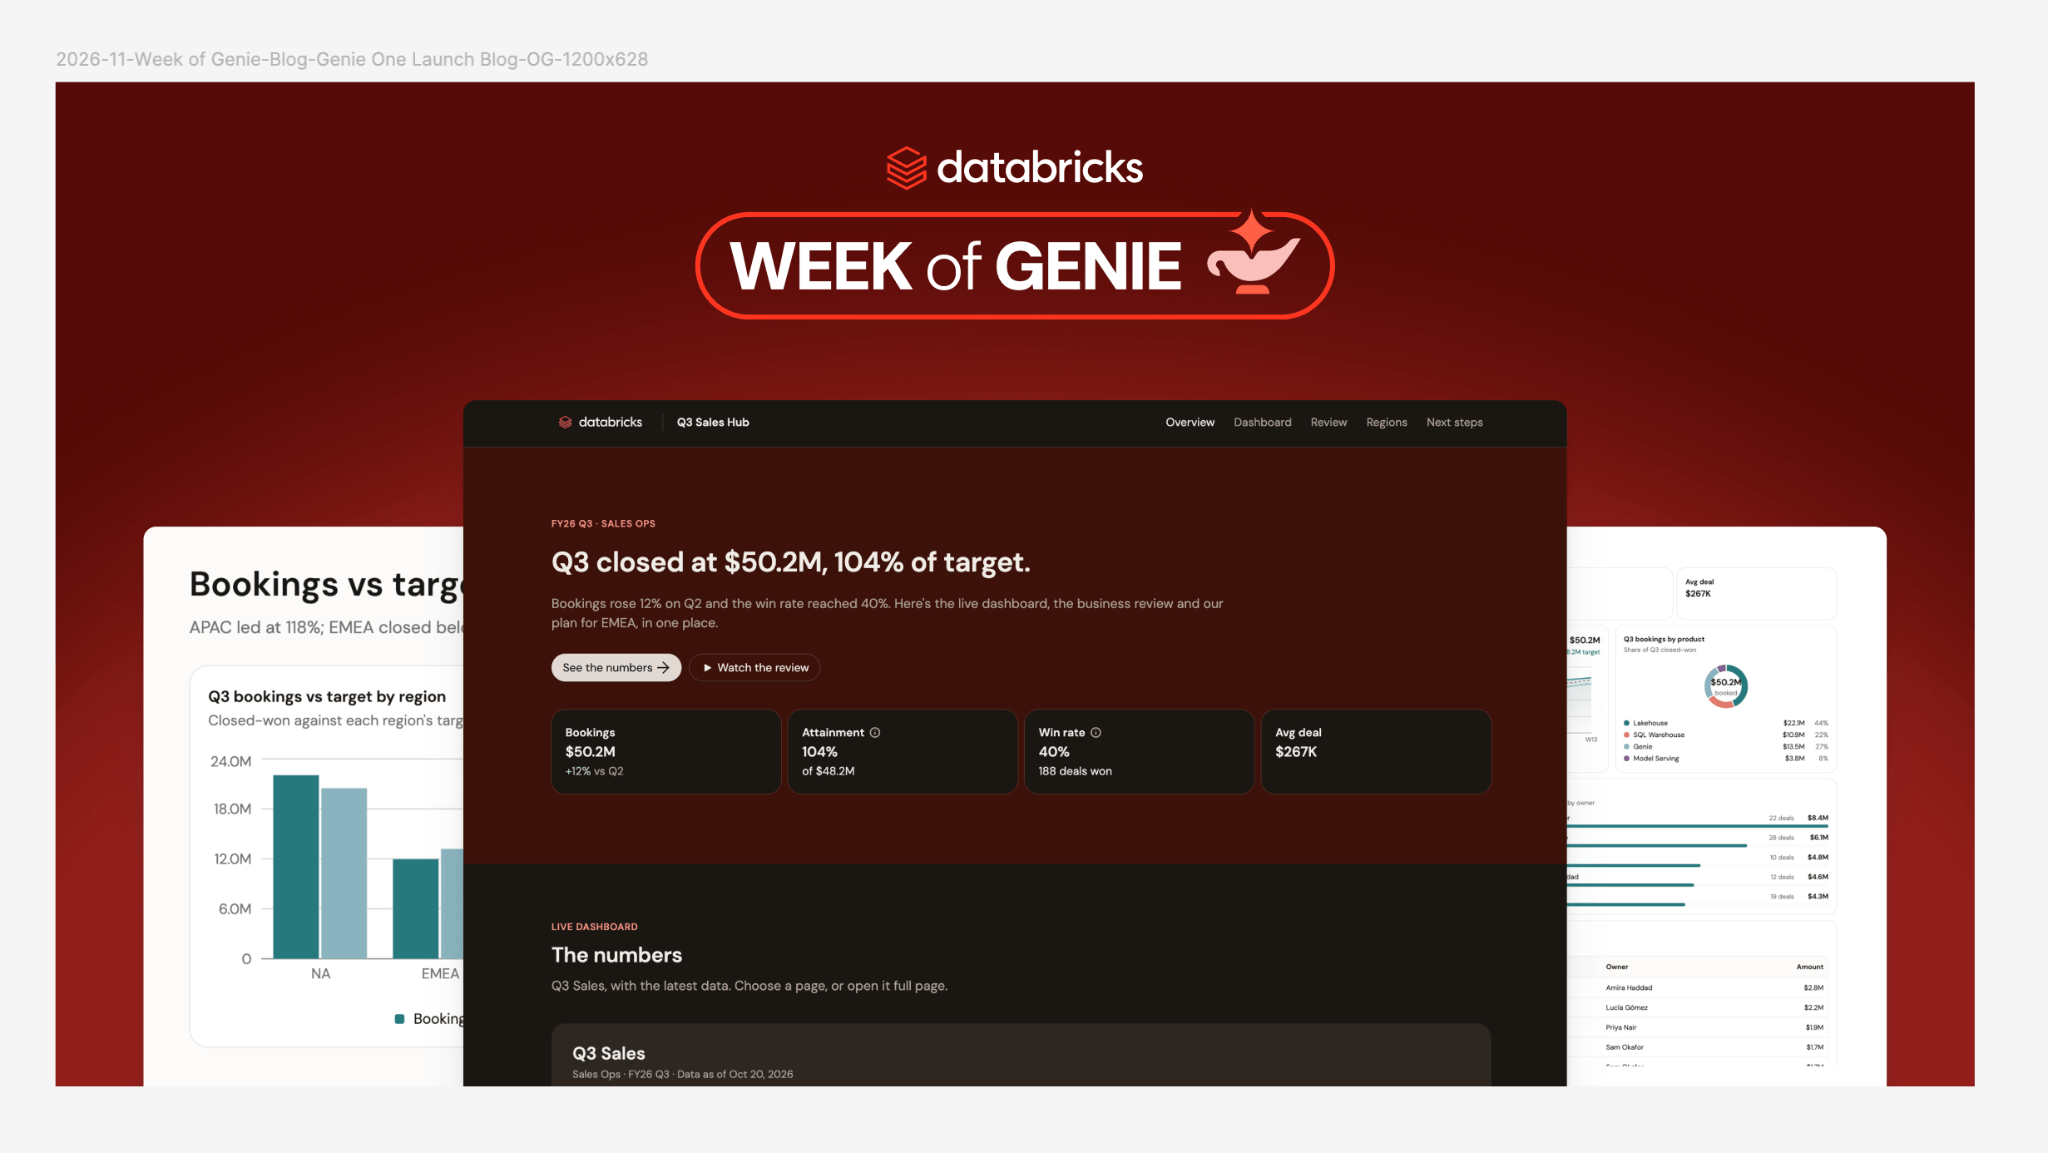
Databricks introduced the new Genie, an autonomous AI coworker that stays on the job continuously, tracking pr…
The New York Times reported Jensen Huang allegedly had an affair with Alice Huang, a one-time Megaspeed execut…
Plurai raised $13 million in seed funding led by Team8, with U&I, Velocity and Mercer participating, to build…