What happened
The Motley Fool's analyst chose SoundHound AI over Rigetti Computing for 2027, pointing to SoundHound's 6.8x P/S ratio against Rigetti's 251.1x and its target of adjusted EBITDA profitability by the second half of 2027.
Why it matters
The call favors voice AI software that is scaling revenue over quantum hardware still years from commercial viability, a view that could influence retail investors weighing the two stocks.
Summaries like this, every morning.
The comparison lands at a moment when both companies are years away from steady profits but for different reasons. Rigetti's revenue fell 34.3% to nearly $7.1 million in the fiscal year ended Dec. 31, 2025, and nearly 90.2% of it came from U.S. government contracts, a concentration that exposes it to federal budget shifts. SoundHound, by contrast, grew revenue 99.4% to $168.9 million over the same period, though its free cash flow was negative $103.1 million as it invested in acquisitions and platform development.
Both carry no debt-to-equity, but their balance sheets diverge sharply: Rigetti's current ratio of 37.4x gives it far more short-term financial flexibility than SoundHound's 4.6x. Yet the analyst's preference hinges less on liquidity than on trajectory. Rigetti's technology requires cryogenic equipment colder than outer space, an expensive hurdle, while rivals are producing quantum machines that operate at room temperature. SoundHound's path to adjusted EBITDA profitability by the second half of 2027 suggests its losses may narrow as revenue scales.
The valuation gap is the clearest signal. At 251.1x sales, Rigetti is priced for a quantum future that management itself says is at least three years away. SoundHound at 6.8x sales is priced more like a growing software business, even with its own losses. For investors weighing the two for 2027, the analyst's call implies the nearer-term revenue story is the safer bet.
Pick your industry and the AI tools you use, and get news related to your work every day.
Free · 30 seconds with Google · unsubscribe anytimeWhat is AIToday? →
Ask AI anything about this article. The AI reads this article, earlier AIToday articles, and Wikipedia, and cites its sources. Q&As are published on this page for other readers too.
Epic Games, the game maker that has clashed with platform operators including Apple, continues litigation in t…
Treasury Secretary Scott Bessent said on Fox News Sunday that he wants Nvidia's answers within 10 days on whet…
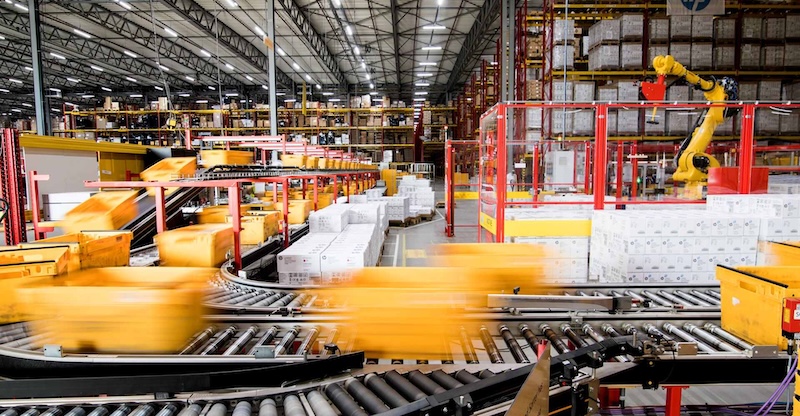
DHL Supply Chain is testing adaptive AI-powered robots and, after a successful proof of concept, has begun int…
Treasury Secretary Scott Bessent told Fox News that Treasury, War, USTR and State backed blacklisting Megaspee…
kickflow raised about ¥700 million through a third-party allotment of new shares, with SMBC Venture Capital an…
Anthropic, the AI developer, is listing at a valuation of 220 trillion yen, a debut that puts a concrete price…