What happened
The developer behind QuantG, an AI quant system for Japanese stocks, moved factor definitions from no specification to themes plus assigned columns, then to information-type definitions with holding periods k of 2 to 20 business days.
Why it matters
Assigning columns alone left 14 of 19 definitions reading daily price, volume or TOPIX, and every candidate was scored on a single 2-day return, so slow-moving valuation signals could not survive.
Summaries like this, every morning.
The three stages trace a shift in what a factor definition is for. In the first stage the developer ported the flow of RD-Agent, an open-source framework for automating factor research, and handed the LLM a daily table with 45 columns built from J-Quants data. The hypotheses that came back clustered on momentum, reversal and volatility, and the other columns went largely unused — not because the model lacked data, but because nobody had a way to constrain where it looked.
The second stage added a two-level research map of six themes and 19 definitions, each definition listing the columns the LLM was allowed to read, with one pool slot per definition so the pool would not tilt in one direction. Slow-disclosure definitions were re-mined roughly every 400 new disclosures while price definitions were re-mined every 3 business days, and the definition count passed 20. Yet in mid-October the pool was still almost entirely daily price and volume transforms, highly correlated with each other, so combining them simply selected high-volatility stocks.
The diagnosis pointed outside the definitions. When the developer re-scored pooled factors at 2, 5, 10 and 20 business days, turnover-liquidity factors rose from an IC of 0.032 to 0.051 at 20 days, while short-term return and market-breadth factors reversed direction at 20 days. A detour of extending every factor to 10 days looked good on 2026 data but collapsed to near zero out of sample on 2023–2024, which is why the current design ties k to the type of information a factor uses rather than to a single universal horizon. The third stage also narrowed each definition to one testable hypothesis and moved evaluation to buying at the next open and selling at the open k business days later.
Pick your industry and the AI tools you use, and get news related to your work every day.
Free · 30 seconds with Google · unsubscribe anytimeWhat is AIToday? →
Ask AI anything about this article. The AI reads this article, earlier AIToday articles, and Wikipedia, and cites its sources. Q&As are published on this page for other readers too.
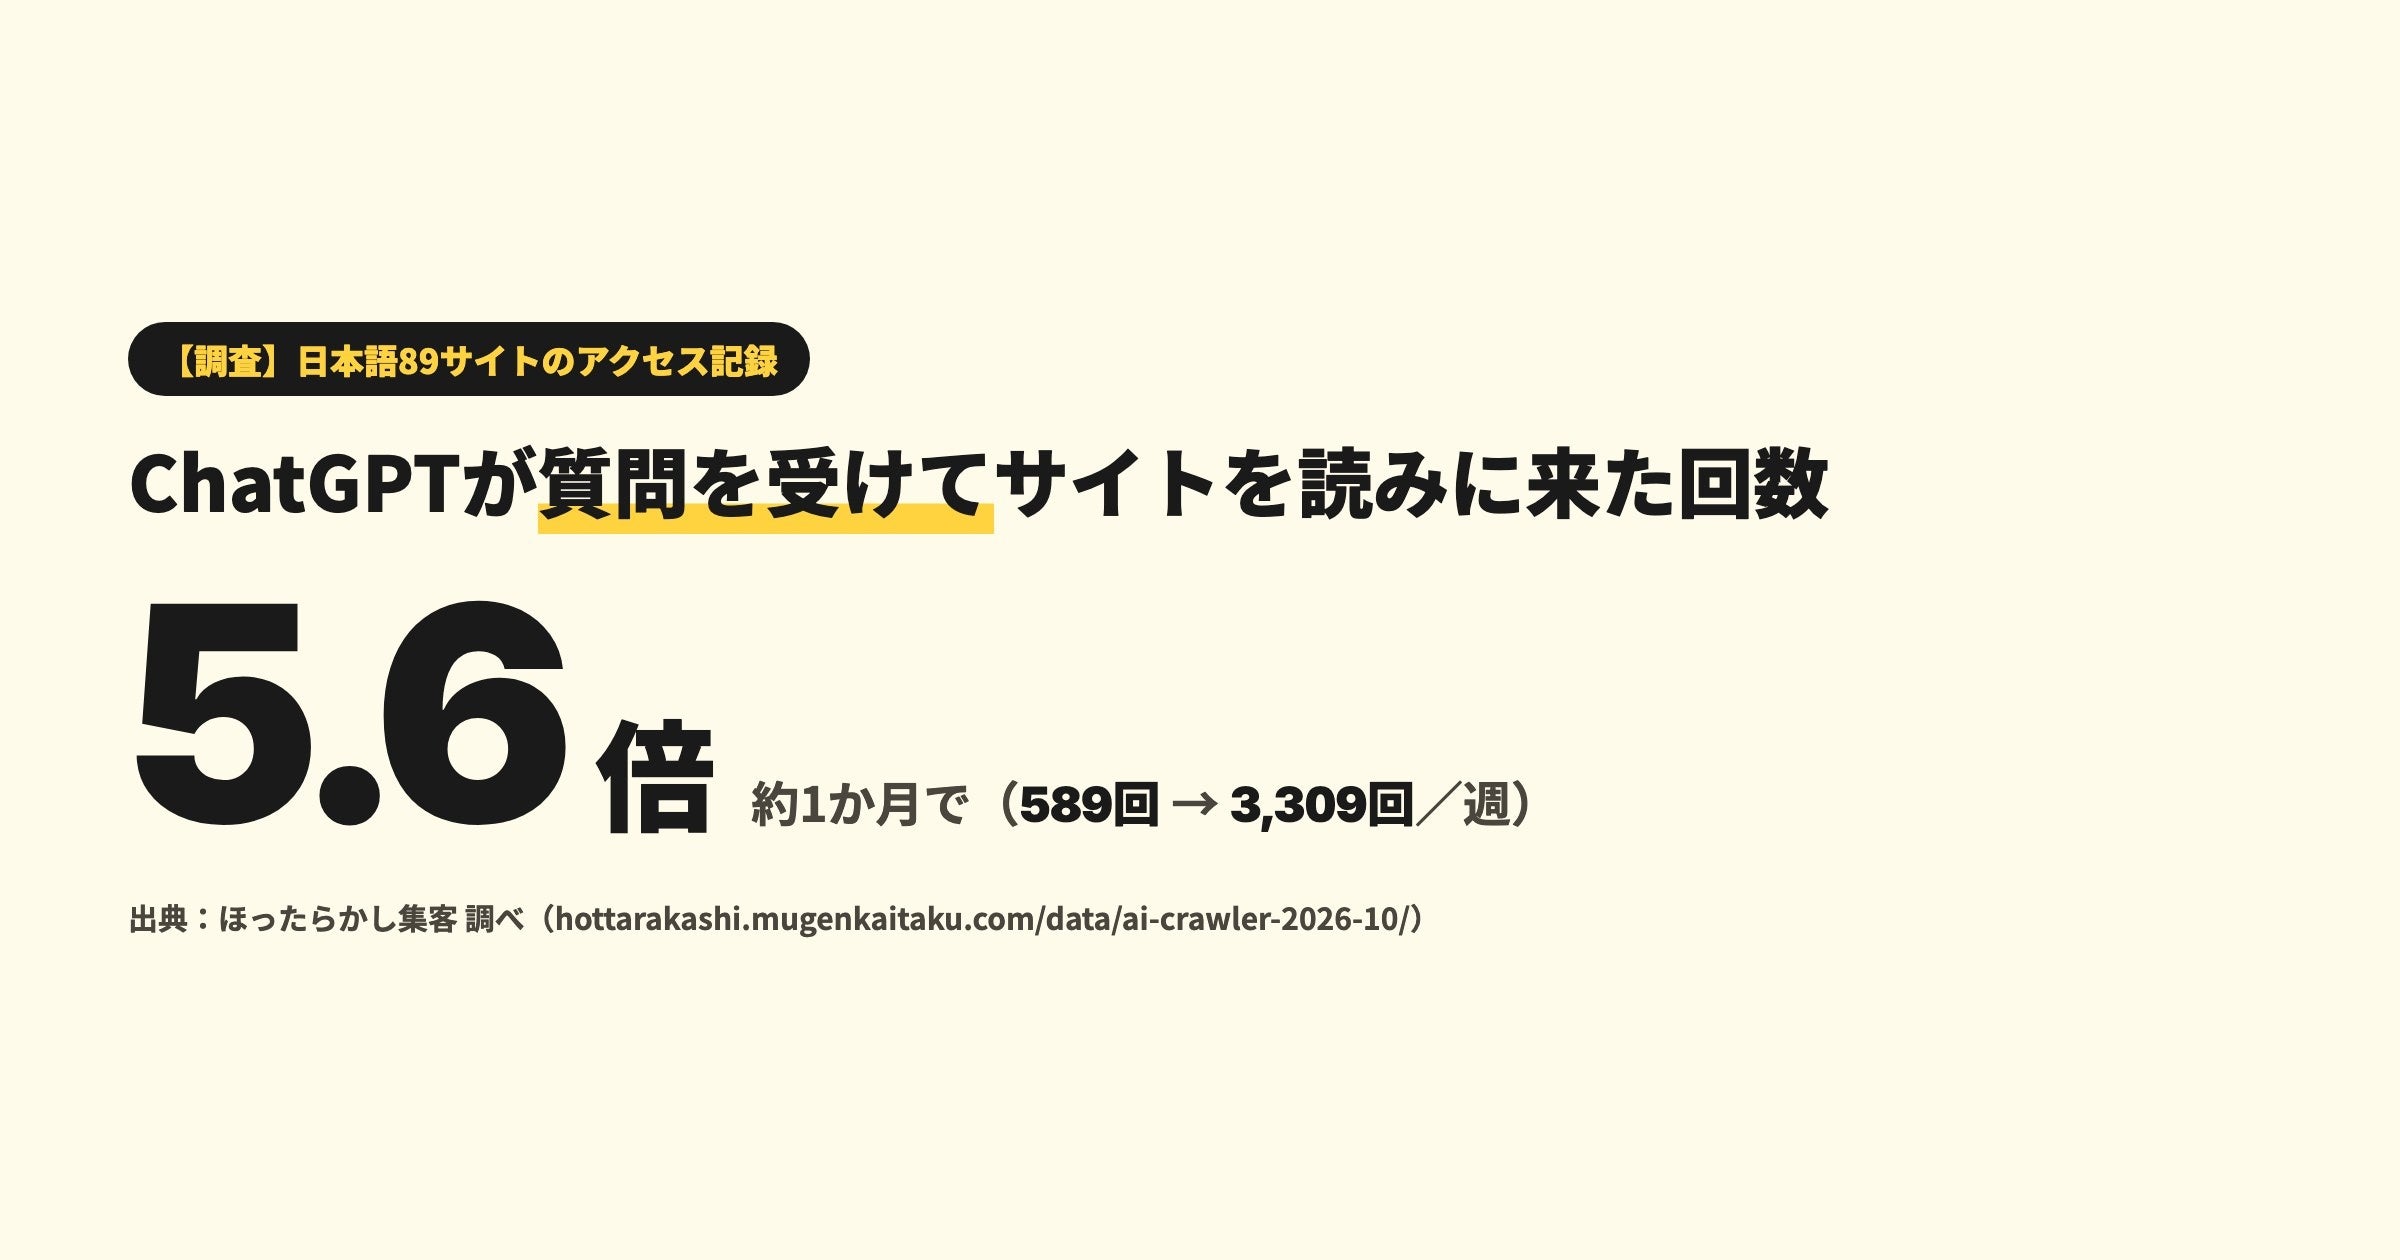
Across 89 Japanese-language sites run by Mugenkaitaku, ChatGPT-User visits rose from 589 in the week of Sept 3…
Uravation began offering a 6-hour hands-on course built on the emergency PHP release of 2026年10月21日, with AI a…

Broadcom reached a deal with several financial firms to finance the purchase of US$63 billion worth of its chi…
NVIDIA and Meta announced they will expand their work on Muse and the Muse family of models to improve inferen…
Nvidia said it will invest $3 billion in Meta Platforms' recent equity offering, part of an expanded partnersh…
ReVia began pre-sales for the AI ONE UltraHub on Makuake on October 24, running through November 29, with supp…