What happened
ServiceNow trades on roughly 80.4x earnings, above the Software industry average near 29.7x and a peer group closer to 26.8x, and the Fair Ratio points lower.
Why it matters
The shares screen as overvalued, leaving less room for disappointment if future profitability or security-related spending differs from what the current multiple implies.
What to watch
Recent critical vulnerabilities on the ServiceNow AI Platform and new security partnerships mean the valuation hinges on whether sustained investment is needed to support trust and resilience.
WHO IT HITSInvestors holding or evaluating ServiceNow shares face a valuation that already prices in premium earnings, leaving little cushion if security spending rises or profit trends disappoint.
Summaries like this, in your inbox every morning.
ServiceNow's share price has fallen 29.4% over the past year, which has brought fresh attention to whether the current valuation is supported by the earnings the business generates today and what it can plausibly earn in the future. The central yardstick in this debate is the P/E ratio, which sits at roughly 80.4x — materially richer than the Software industry average near 29.7x and a peer group closer to 26.8x. The Fair Ratio, a benchmark blending growth outlook, profitability profile, risk and size, points to a lower level than the current multiple, reinforcing the overvalued screen.
Recent security issues around critical vulnerabilities on the ServiceNow AI Platform, along with new security-focused partnerships, add another layer. These developments may influence how investors think about future spending needs and customer trust, which in turn could affect how much profit the business retains from its revenue. In other words, the earnings multiple already prices the stock at a premium, and the security situation suggests the company may need sustained investment to support trust and resilience.
What the current price ultimately hinges on is whether future profitability trends and security-related spending play out in line with what the 80.4x P/E implies. If they differ, there is less room for disappointment given the premium to sector and peer norms. Narratives on ServiceNow, which spell out earnings paths or margin profiles that would make the current P/E look conservative or stretched, may offer a useful framework for investors as fresh information arrives.
Pick your industry and the AI tools you use, and get news related to your work every day.
Free · 30 seconds with Google · unsubscribe anytimeWhat is AIToday? →
Ask AI anything about this article. The AI reads this article, earlier AIToday articles, and Wikipedia, and cites its sources. Q&As are published on this page for other readers too.
BlackRock's research paper "The Machine-Native Economy," co-written by digital assets head Robert Mitchnick, a…
Palo Alto Networks launched Cortex XCOR, an AI-native observability platform
John Deere announced JD, an AI assistant embedded in its Operations Center, at a press event at Iowa State Uni…
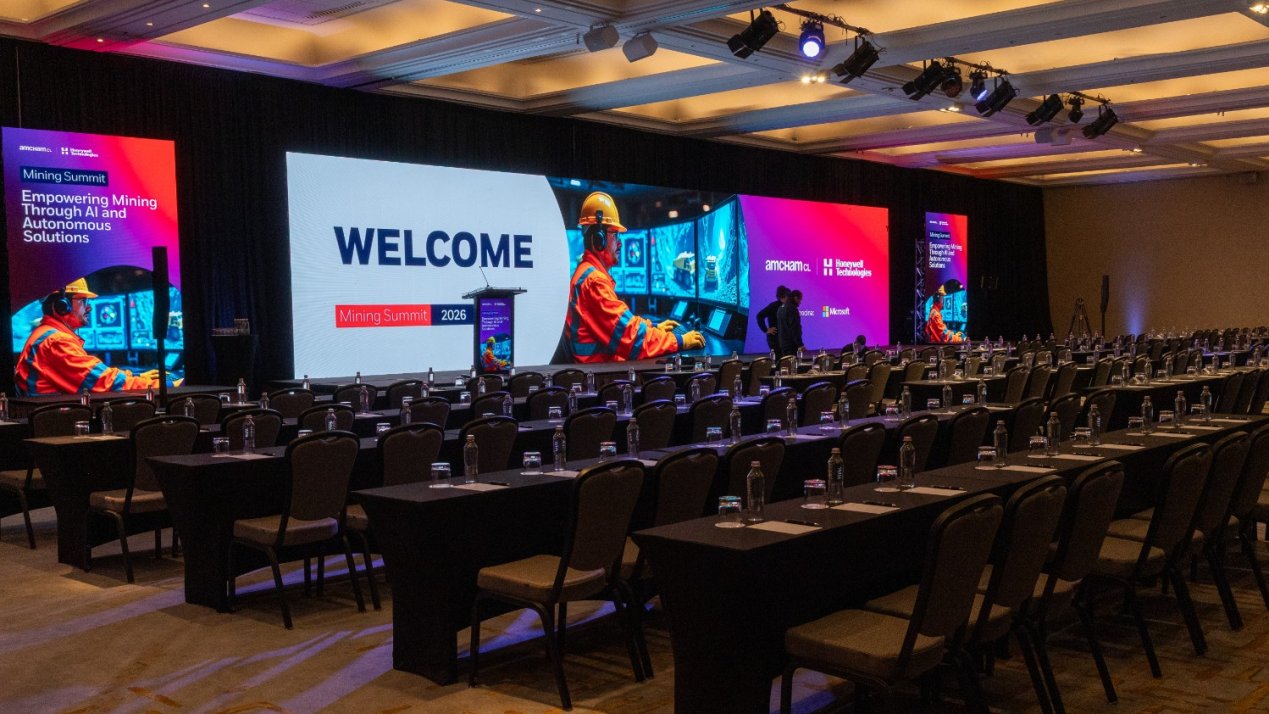
At a Sept. 24 Santiago summit organized by AmCham Chile and Honeywell, Honeywell's José Simón proposed expandi…
Salesforce trades at a 14.4x forward P/E versus Palantir's 85.5x, and Agentforce annual recurring revenue pass…
CrowdStrike Holdings has listed its Falcon cybersecurity platform in the OpenAI Marketplace for enterprise buy…