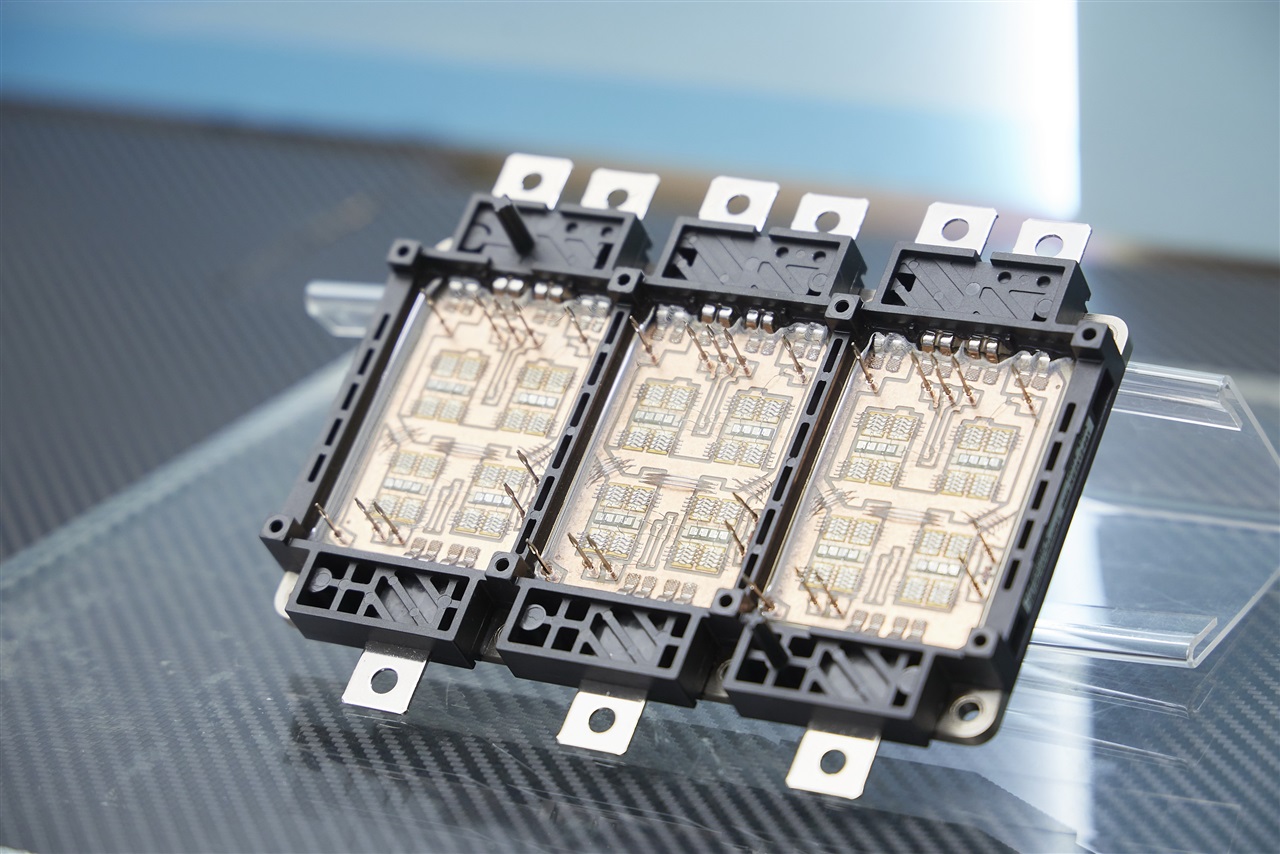
What happened
DIGITIMES reported the SiC substrate market is finally seeing signs of recovery, after prices collapsed when weakening EV demand hit SiC power devices. By 2026, EVs are estimated to account for 65% of SiC device applications.
Why it matters
The recovery signals that the sharp price decline in SiC substrates may be bottoming out as demand from EVs, renewable energy, and AI infrastructure strengthens. The 65% EV share estimate, if it holds, would make electric vehicles the largest application segment for SiC devices.
What to watch
The rebound hinges on whether demand from vehicles, energy, and AI can absorb the aggressive capacity that suppliers built during the boom. Watch six-inch SiC substrate prices in 2027, when DIGITIMES expects the initial rebound to take hold.
WHO IT HITSThis recovery matters most for SiC substrate suppliers and power device makers who ramped up capacity aggressively and have been squeezed by collapsing prices. It also affects EV manufacturers and AI data center operators who depend on SiC components for traction inverters and high-voltage power systems.
Summaries like this, every morning.
The SiC substrate market's boom-and-bust cycle began in 2018, when Tesla equipped the Model 3 with a traction inverter integrated with SiC power modules, prompting suppliers to aggressively ramp up capacity. As EV momentum weakened, demand for SiC power devices fell sharply and substrate prices collapsed. Now, with the EV market gradually recovering and renewable energy deployment expanding, the market is finally seeing signs of recovery. The planned high-voltage direct current (HVDC) power architecture for AI data centers is also expected to further stimulate demand for SiC substrates.
This recovery comes as the EV industry has broadly adopted SiC power devices in traction inverters, with Chinese brands like BYD, NIO, Xpeng Motors, Li Auto and Xiaomi, plus global automakers such as Porsche, Hyundai Motor Company, GM, BMW, Audi and Mercedes-Benz all following Tesla's lead. By 2026, EVs are estimated to account for 65% of SiC device applications, making them the largest application segment. The report also covers key applications of SiC substrates, their cost breakdown, major suppliers and their capacity expansion plans.
Whether the rebound holds will depend on how quickly demand from vehicles, energy and AI infrastructure absorbs the aggressive capacity that suppliers built during the boom years. For substrate suppliers and power device makers, the test is whether the projected initial rebound in six-inch SiC substrate prices in 2027 materializes, and whether the high-voltage direct current architecture planned for AI data centers from 2027 to 2028 becomes a meaningful new source of demand.
Pick your industry and the AI tools you use, and get news related to your work every day.
Free · 30 seconds with Google · unsubscribe anytimeWhat is AIToday? →
Ask AI anything about this article. The AI reads this article, earlier AIToday articles, and Wikipedia, and cites its sources. Q&As are published on this page for other readers too.
Ace Pillar, a Qisda Group affiliate, reported strong third-quarter 2026 results as its semiconductor, AI autom…
Microsoft entered a new AI partnership with Cerebras, whose AI hardware and software will be used within Micro…
An analysis lays out how Dell Automation Platform uses a portal, catalog and orchestrator to apply reusable bl…
Thailand's National Economic and Social Development Council said real GDP rose 2.9% year-on-year in July–Septe…
Internal documents seen by Reuters show Amazon plans a "World Product Graph" catalog of global product data, i…
株式会社粋農 implemented MCP (Model Context Protocol, a common standard linking AI apps to external data and functio…


