What happened
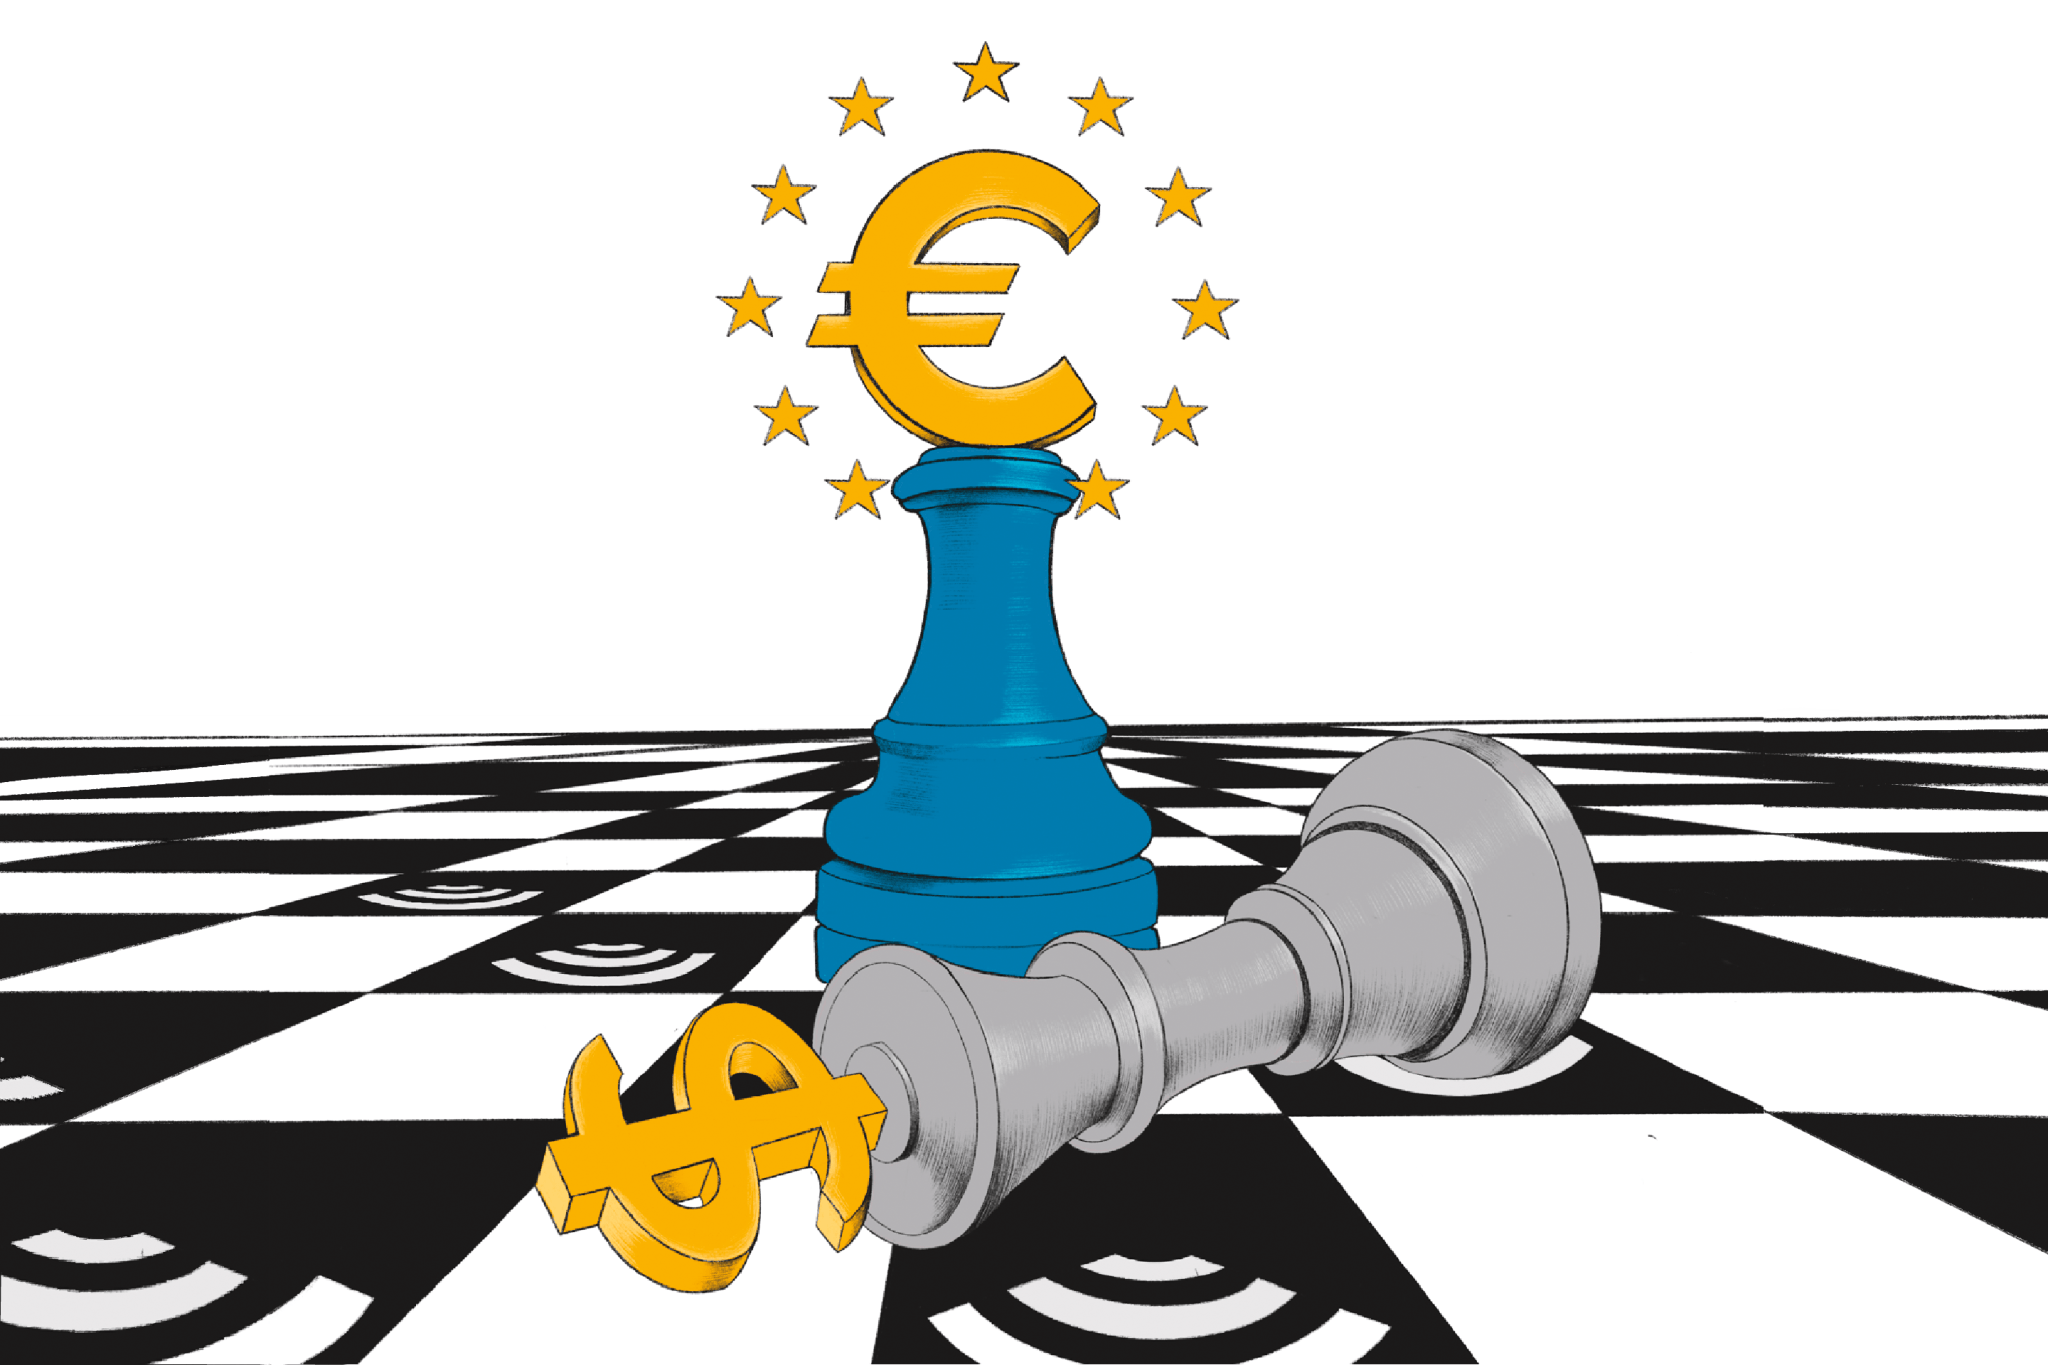
The European Parliament's economic affairs committee voted 43 to 14 to back the ECB's digital euro, a €1.3 billion project, with a 12-month pilot scheduled to start in the second half of 2027.
Why it matters
The vote keeps the ECB's plan for a free, universally accepted public payment option moving toward launch, with 36 finance firms signed up for the pilot and businesses expected to accept it by 2029.
What to watch
The real test is whether it achieves broad everyday adoption, and its track record elsewhere is weak — the Eastern Caribbean's DCash pilot was suspended in 2024 and Nigeria's eNaira has seen limited adoption. Watch the ECB's estimated €4 billion to €6 billion ($4.7 billion to $7 billion) cost to European banks.
WHO IT HITSEuropean retailers and merchants would face a mandate to accept digital euros in-store and online by 2029, and banks would have to offer it to customers while running a second payment system alongside their existing one.
Summaries like this, in your inbox every morning.
The digital euro has taken six years to reach the pilot stage, and it arrives in a crowded field. BNP Paribas, Commerzbank, and Rabobank have all backed Wero, a bank-funded digital wallet that has 50 million users, raising questions about whether Europe is developing two solutions to the same strategic problem. Meanwhile, Washington rejected its own digital dollar and passed the GENIUS Act to support private, dollar-backed stablecoins, which handled roughly $33 trillion in transactions in 2025.
Europe's payment landscape is fragmented: 15 of the euro area's 21 countries still lack a domestic digital payment solution, and national schemes like iDEAL, Bizum, and Blik create different checkout experiences in each market. Physical cash is also fading — the share of eurozone companies not accepting cash has tripled to 12% over the past three years, according to the ECB.
The digital euro carries mandatory merchant acceptance and mandatory distribution through banks, which could make it a cheaper alternative by letting merchants sidestep interchange fees and settle instantly. But researchers say the case for it isn't obvious to ordinary people, and similar efforts elsewhere have been, in one lawyer's words, "complete and utter flops." Whether it succeeds may hinge on whether consumers and banks embrace a system whose costs they will partly bear — and on whether it arrives before private alternatives become entrenched.
Pick your industry and the AI tools you use, and get news related to your work every day.
Free · 30 seconds with Google · unsubscribe anytimeWhat is AIToday? →
Ask AI anything about this article. The AI reads this article, earlier AIToday articles, and Wikipedia, and cites its sources. Q&As are published on this page for other readers too.
DIGITIMES reported the SiC substrate market is finally seeing signs of recovery, after prices collapsed when w…
HENNGE said on October 1 it set up HENNGE AI, a subsidiary with only two directors and no other employees, whe…
Pershing Square sold its entire Alphabet stake and topped off Microsoft while it sat about 20% below its Q2 hi…
Aolani will integrate Karman's power orchestration platform, built on a custom NVIDIA Jetson Orin Nano and tar…
CloudNC raised $20 million led by Nimble Ventures, with Calculus Venture Capital, Entrepreneur First and LM Ve…
Pony.ai and Verne began fully driverless Robotaxi test rides with passengers on public roads in Zagreb, along…